
Where this fits: The last chapter explained what the securities market does. Before you meet the people who run it or the products you will actually buy, you need to know what the instruments themselves are. Everything later in this book is built from the three in this chapter.
By the end of this chapter you will be able to
- State the single difference that separates every security into one of two families
- Explain what a share, a bond and a mutual fund unit each give you a claim on
- Say why a mutual fund is not a fourth kind of thing, but a container for the first two
Two families, one question
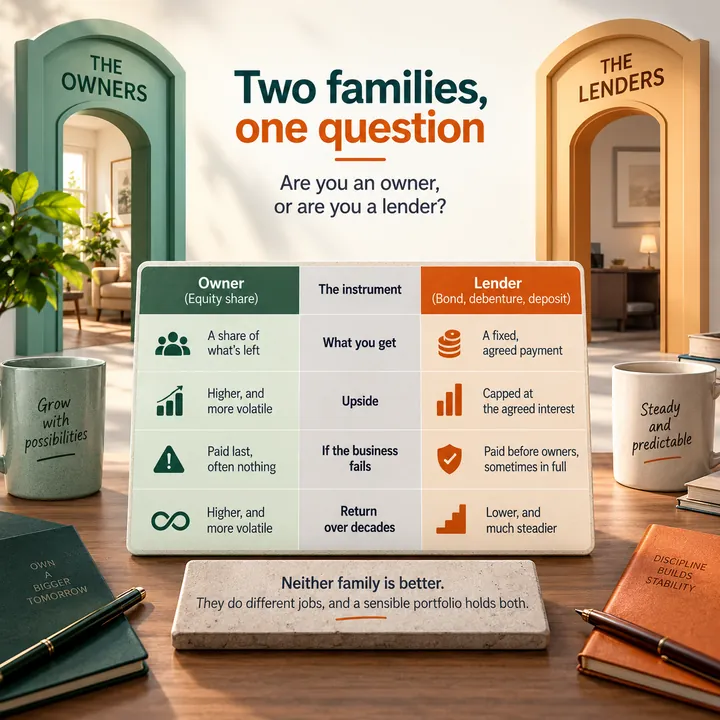
There are thousands of securities listed in India and more are created every week. Almost all of them answer one question: are you an owner, or are you a lender?
That single distinction determines what you are entitled to, where you stand if things go wrong, and what your realistic return looks like. Learn it once and most of the market becomes readable.
| Owner | Lender | |
|---|---|---|
| The instrument | Equity share | Bond, debenture, deposit |
| What you get | A share of whatever is left after everyone else is paid | A fixed, agreed payment |
| Upside | Unlimited in principle | Capped at the agreed interest |
| If the business fails | Paid last, often nothing | Paid before owners, sometimes in full |
| Return over decades | Higher, and much more volatile | Lower, and much steadier |
Neither family is better. They do different jobs, and a sensible portfolio holds both.
Equity shares — you are an owner
An equity share represents part-ownership of a company. If a company has issued one crore shares and you own 100, you own one hundred-thousandth of it.
Ownership gives you:
- A claim on profits, which the company may distribute as dividends
- Voting rights on certain resolutions, in proportion to your holding
- A claim on the residual value if the company is wound up — after every creditor, lender and preference shareholder has been paid
That last point defines equity risk precisely. As an owner you are last in the queue. You share fully in the upside and you absorb the losses first. It is the reason equity has produced higher long-term returns than debt, and the reason it can fall 40% in a year.
Two things a share does not give you. It does not entitle you to any particular price — the price is whatever another investor will pay today. And it does not entitle you to a dividend; companies may pay one, reduce it, or stop.
Watch Out — the company’s profit is not your profit
A company can grow revenue and profit for years while its share price falls, because the price already reflected an even better outcome. What you earn depends on the price you paid relative to what the business eventually delivers, not on the business alone.
Bonds and debentures — you are a lender
A bond or debenture is a loan. You lend money to a government or a company for a fixed period. In return you receive:
- Coupon — interest, usually paid at fixed intervals
- Principal — the original amount, returned at maturity
As a bondholder you are paid before shareholders, in good times and in bad. Your return is capped at the agreed interest — the company tripling its profits does not increase your coupon — and your risk is that the borrower fails to pay.
That asymmetry is why debt is the stabilising element in a portfolio, and why it will not, on its own, beat inflation over decades.
Government bonds carry effectively no credit risk in domestic currency. Corporate bonds pay more and carry more. Both carry a second risk that surprises people, because it has nothing to do with default: when interest rates rise, the market price of an existing bond falls. The arithmetic of that is worked through later, in the chapter on bonds. For now, note only that “safe” does not mean “the price never moves.”
Mutual fund units — a claim on a pool of the above
Here is the point that trips up most first-time investors, and it is worth stating plainly.
A mutual fund is not a third kind of security. It is a container for the first two.
When you buy a unit of a mutual fund, you are not buying something new. You are buying a proportionate claim on a pool of shares and bonds that the fund holds on your behalf. An equity fund is shares. A debt fund is bonds. A hybrid fund is both, in a stated proportion.
This has three consequences that matter more than anything else you will read about mutual funds:
- The fund’s risk is the risk of what it holds: An equity mutual fund carries equity risk in full. The word “fund” does not soften it, the fund manager cannot remove it, and no amount of diversification within the fund makes shares behave like deposits.
- The fund’s return is the return of what it holds, minus costs: There is no separate source of profit. If Indian companies collectively do well, equity funds do well.
- You still need to know what shares and bonds are: Choosing between an equity fund and a debt fund is choosing between being an owner and being a lender. It is the same decision, taken through a professional.
What the fund genuinely adds is real and worth paying a little for: diversification you could not afford on your own, professional selection, daily valuation, and the operational machinery to buy ₹500 worth of fifty companies at once. What it cannot add is a return without the corresponding risk.
Worked Example — the same rupee, two ways
You have ₹50,000 and want exposure to fifty large Indian companies.
Directly: you would need to research fifty businesses, place fifty orders, pay fifty sets of charges, and hold odd lots in a demat account. With ₹50,000 you could buy a meaningful quantity of perhaps two or three.
Through a fund: one instruction, one charge, and your ₹50,000 buys a proportionate slice of all fifty.
In both cases you own shares in fifty companies. The instrument you hold has a different name; the underlying exposure is identical.
Two more you will meet
Exchange Traded Funds (ETFs): A fund that tracks an index or a commodity and trades on the exchange like a share. Same container principle, bought a different way, usually at very low cost.
Derivatives — futures and options: Contracts whose value derives from an underlying asset such as a share, an index or a commodity.
| Returns | Risk | |
|---|---|---|
| Can be very high, and are leveraged | Very high. Losses can exceed the amount you put in | |
| Watch Out — a plain warning about derivatives Derivatives are legitimate instruments used by institutions to hedge genuine risks. They are also the fastest route by which retail investors lose money in the Indian market. Studies published by SEBI on individual traders in the equity derivatives segment have repeatedly found that a large majority lose money, with average losses that are substantial. This book will explain what derivatives are, and will not teach you to trade them. If you have read this far, your capital belongs in the products this book does cover, not here. |
Putting the three together
| Equity share | Bond | Mutual fund unit | |
|---|---|---|---|
| You are | An owner | A lender | An owner of a pool |
| Equity share | Bond | Mutual fund unit | |
| Your claim is on | One company | One borrower | Everything the scheme holds |
| Income | Dividends, if declared | Coupon, as agreed | Whatever the pool generates, after costs |
| Diversified by default | No | No | Yes |
| Priced | Continuously, on the exchange | On the exchange or at maturity | Once a day, at NAV |
| Needs a demat account | Yes | Usually | No, unless held in demat form |
Recap in one minute
- Almost every security makes you either an owner or a lender. That one distinction explains most of the market.
- An equity share is part-ownership: last in the queue, unlimited upside, no promise of price or dividend.
- A bond is a loan: paid before owners, return capped at the coupon, and its market price falls when interest rates rise.
- A mutual fund unit is not a third instrument. It is a proportionate claim on a pool of shares and bonds, and it carries exactly the risk of what it holds.
- A fund adds diversification, professional selection and convenience. It cannot add return without the matching risk.
Check your understanding
A company announces record profits and its share price falls the same day. Has something gone wrong with your investment?
Show answer to question 1
No. A share price reflects what investors already expected. A record profit that is smaller than what the market had priced in can send the price down. Your outcome depends on the price you paid relative to what the business eventually delivers.Your friend says an equity mutual fund is “safer than shares because it is a fund.” What is right and what is wrong in that statement?
Show answer to question 2
Right: a fund holds many companies, so the failure of any one of them hurts far less. Wrong: it is not safer than shares as an asset class. An equity fund carries equity risk in full, and can fall heavily when the market falls.You want your money returned on a fixed date with a known amount. Which family should you be looking at, and why?
Show answer to question 3
The lender family — a bond, deposit or similar instrument. Only a lender has an agreed amount on an agreed date. An owner has a claim on whatever is left, which is never fixed in advance.
Your action step
Take any one mutual fund scheme — yours, a family member’s, or any scheme picked at random from an AMC website. Find its portfolio disclosure, which every scheme publishes monthly. Look at what it actually holds. Write down the top five holdings and whether each is a share or a bond. You are looking at what you would really own.
